
5 Mistakes to Avoid when Refinancing Your Mortgage
Mortgage refinancing is an activity currently being pursued by many Australians to reduce cost-of-living pressures. As home loan repayments form a large part of the household budget, it is crucial to consider all the factors involved before switching lenders.
While it’s true that mortgage refinancing may help save money on monthly loan repayments and thereby improve your financial situation, it requires proper due diligence to ensure that this outcome occurs.
Here are the top 5 common mistakes to avoid when refinancing your mortgage in Australia:
-
Focusing Purely on Interest Rates
 One of borrowers’ most significant mistakes when refinancing their mortgage is concentrating solely on interest rates. While interest rates are undoubtedly essential in finance industry, they are not the only factor to focus on during the process to avoid this mistake, you need to consider loan features, terms and fees for better outcomes.
Furthermore, during your evaluation, consider whether the loan offers flexible repayment options that align with your financial goals. Remember, a lower interest rate with inflexible terms that don’t suit your needs might not be as advantageous as you think it might be.
-
Brushing Off the Exit Fees
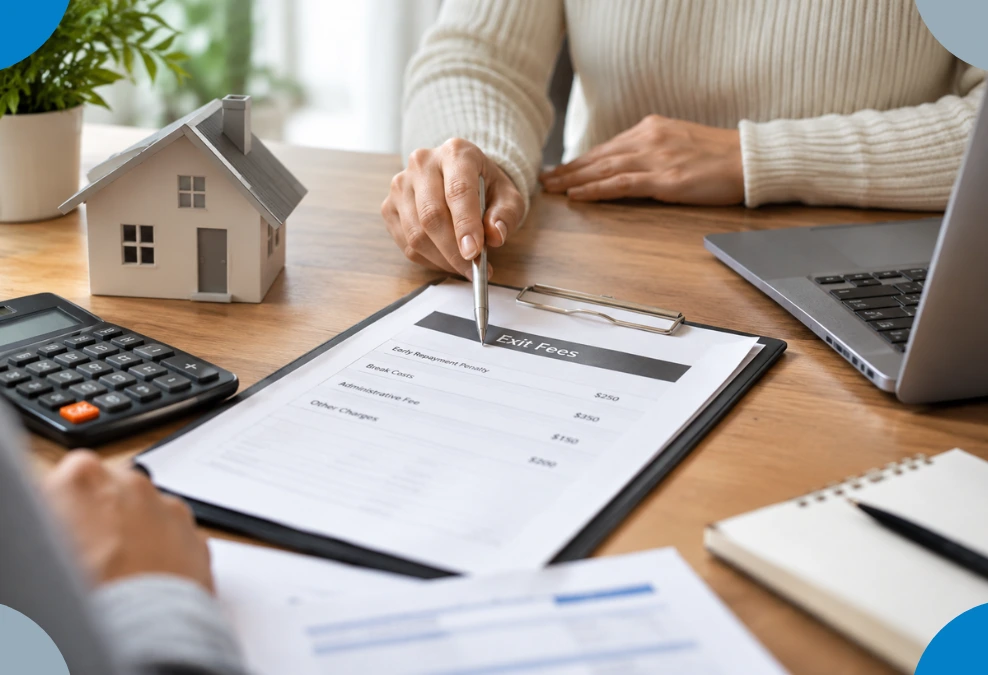 Exiting your current mortgage may incur exit fees or early repayment penalties. Many borrowers make the mistake of underestimating these charges, assuming they’re negligible. Exit fees can be substantial, so it’s vital to understand how much you may be charged for leaving your current lender before you refinance with a new lender.
-
Reluctant to Change Current Lender
Many homeowners hesitate to change their current lender, but staying loyal to one institution may not be the most financially advantageous choice. Alternative lenders often offer better loan terms, lower interest rates, and meaningful cost savings. Therefore, it is best to explore all your options and switch lenders if it benefits you financially during the mortgage refinancing process.
-
Falling for Initial Rate Offers
Lenders frequently promote enticing initial rate offers to attract borrowers. However, these rates may only be introductory rates, which means they can increase significantly after a certain period. It’s essential to read the fine print, understand how long the initial rate lasts, and what the ongoing rates will be. Look for loans that provide long-term affordability, not just short-term appeal.
-
Going without a Broker in the Refinance Process
 While many Australian borrowers opt to navigate the mortgage refinancing process on their own, this can be a costly mistake. Mortgage brokers have extensive industry knowledge and can help you effectively navigate the complex world of refinancing. They can save you time and potentially secure better deals with lenders.
To Wrap It Up
Refinancing your mortgage can offer substantial financial benefits when done right. Staying away from these 5 mortgage refinancing mistakes can help you make a well-informed decision that aligns with your long-term financial goals.
Oz Lend is here to help you make the most of your refinancing journey and achieve a brighter financial future. Our team of experienced mortgage brokers can analyse your financial situation, provide advice tailored to your needs, and help you find the most suitable loan options.
Are you ready for mortgage refinancing? Talk to one of our expert mortgage brokers now!
FAQ's
There is no fixed waiting period, but many borrowers consider refinancing after building some equity or when a better loan option becomes available. Your eligibility will depend on your lender’s requirements, your financial position and the value of your property.
Refinancing usually involves a credit enquiry, which may have a small temporary impact on your credit score. However, making repayments on time and avoiding multiple loan applications within a short period can help maintain a healthy credit profile.
Yes. Your property’s current market value plays an important role in refinancing. If your property’s value has increased, you may have access to better loan options. If it has decreased, your available choices may be more limited.
Yes. Self-employed borrowers can refinance, although lenders may ask for additional financial documents, such as tax returns, business financial statements or BAS statements, to assess income stability.
Yes. Many homeowners refinance to access part of their property’s available equity for approved purposes such as renovations, debt consolidation or investing. The amount available depends on your property’s value and your existing loan balance.
Most lenders require proof of identity, recent payslips or income documents, bank statements, details of your current mortgage and information about your assets and liabilities. Additional documents may be requested depending on your circumstances.
It depends on your timeline and the costs involved. If you expect to sell your property soon, refinancing fees and associated costs may outweigh any potential savings. A financial assessment can help determine whether refinancing is worthwhile.
In some situations, refinancing may allow eligible borrowers to consolidate debts into their home loan. While this can simplify repayments, it is important to understand the long-term costs before proceeding.
In many cases, yes. Lenders often arrange a property valuation to determine your home’s current market value before approving a refinance application. This helps them assess the level of lending risk.
Look beyond the advertised interest rate and compare the total cost of the loan over time. Consider application fees, discharge fees, ongoing charges, loan features and the total interest payable to determine whether refinancing provides genuine long-term savings.